


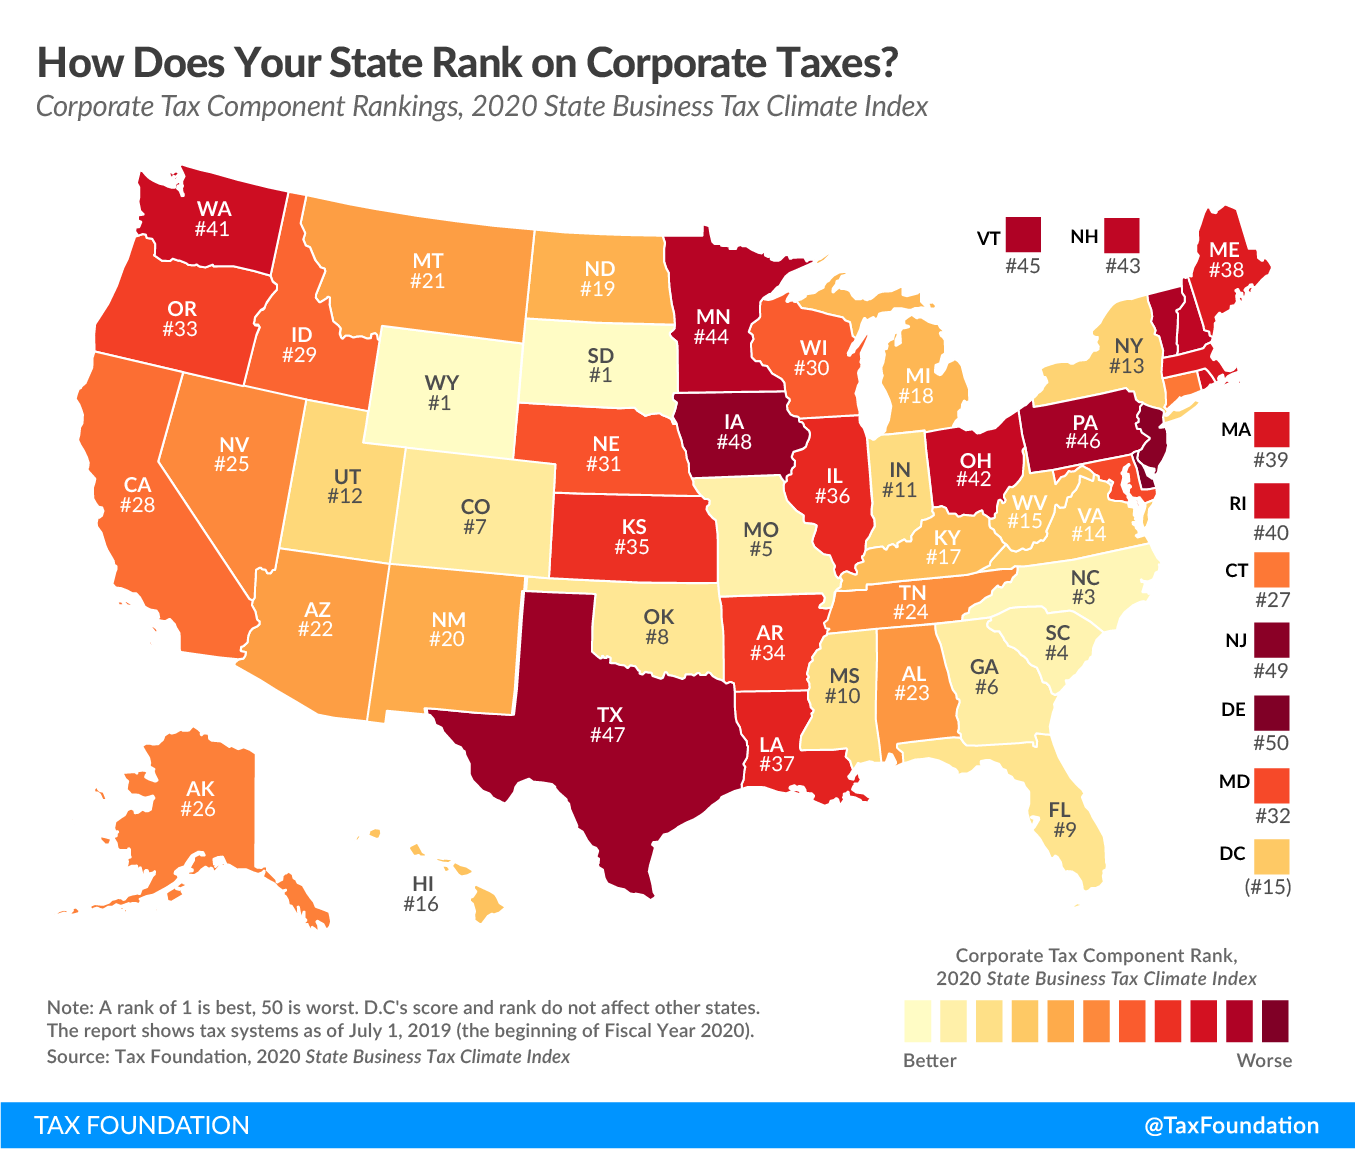
In the coming weeks, we will break down our recently released 2020 State Business Tax Climate Index with maps illustrating each of the five major components of the Index: corporate, individual, sales, property, and unemployment insurance taxes. Today we look at states’ rankings on the corporate tax component, which accounts for 19.7 percent of each state’s overall rank.
The corporate tax component of our Index measures each state’s principal tax on business activities. Most states levy a corporate income tax on a company’s profits (receipts minus most business expenses, including compensation and the cost of goods sold), while some states levy gross receipts taxes, which allow few or no deductions for a company’s expenses.
Unlike other studies that look solely at tax burdens, the Index measures how well or poorly each state structures its tax system. It is concerned with the how, not the how much, of state revenue, because there are better and worse ways to levy taxes. Our corporate tax component, for example, scores states not just on their corporate tax rates and brackets, but also on how they handle net operating losses, whether they levy gross receipts-style taxes (which are more economically harmful than corporate income taxes), whether businesses can fully expense purchases of machinery and equipment, and whether states index their brackets for inflation, among other factors.
Click here to see an interactive version of states’ corporate tax rankings, and then click on your state for more information about how its tax system compares both regionally and nationally.
| State | 2020 Rank | 2019 Rank | Change from 2019 to 2020 | 2018 Rank | 2017 Rank |
|---|---|---|---|---|---|
|
Note: A rank of 1 is best, 50 is worst. All scores are for fiscal years. DC’s score and rank do not affect other states. Source: Tax Foundation. |
|||||
| Alabama | 40 | 40 | 0 | 39 | 38 |
| Alaska | 3 | 3 | 0 | 3 | 3 |
| Arizona | 20 | 20 | 0 | 19 | 18 |
| Arkansas | 46 | 46 | 0 | 42 | 42 |
| California | 48 | 49 | -1 | 48 | 48 |
| Colorado | 17 | 16 | 1 | 17 | 19 |
| Connecticut | 47 | 47 | 0 | 47 | 47 |
| Delaware | 11 | 11 | 0 | 20 | 20 |
| Florida | 4 | 4 | 0 | 4 | 4 |
| Georgia | 32 | 36 | -4 | 34 | 34 |
| Hawaii | 37 | 37 | 0 | 26 | 26 |
| Idaho | 21 | 21 | 0 | 21 | 21 |
| Illinois | 35 | 35 | 0 | 28 | 24 |
| Indiana | 10 | 10 | 0 | 8 | 8 |
| Iowa | 42 | 43 | -1 | 44 | 43 |
| Kansas | 34 | 27 | 7 | 27 | 28 |
| Kentucky | 24 | 24 | 0 | 37 | 37 |
| Louisiana | 41 | 41 | 0 | 46 | 46 |
| Maine | 33 | 31 | 2 | 36 | 35 |
| Maryland | 43 | 42 | 1 | 40 | 40 |
| Massachusetts | 36 | 33 | 3 | 29 | 31 |
| Michigan | 12 | 17 | -5 | 12 | 12 |
| Minnesota | 45 | 44 | 1 | 43 | 44 |
| Mississippi | 31 | 30 | 1 | 32 | 32 |
| Missouri | 14 | 14 | 0 | 15 | 15 |
| Montana | 5 | 5 | 0 | 6 | 6 |
| Nebraska | 28 | 26 | 2 | 31 | 30 |
| Nevada | 7 | 6 | 1 | 5 | 5 |
| New Hampshire | 6 | 7 | -1 | 9 | 9 |
| New Jersey | 50 | 50 | 0 | 50 | 50 |
| New Mexico | 22 | 23 | -1 | 24 | 25 |
| New York | 49 | 48 | 1 | 49 | 49 |
| North Carolina | 15 | 12 | 3 | 10 | 10 |
| North Dakota | 16 | 15 | 1 | 18 | 17 |
| Ohio | 38 | 38 | 0 | 41 | 39 |
| Oklahoma | 27 | 28 | -1 | 23 | 23 |
| Oregon | 8 | 9 | -1 | 11 | 11 |
| Pennsylvania | 29 | 32 | -3 | 30 | 29 |
| Rhode Island | 39 | 39 | 0 | 38 | 41 |
| South Carolina | 30 | 29 | 1 | 33 | 33 |
| South Dakota | 2 | 2 | 0 | 2 | 2 |
| Tennessee | 18 | 18 | 0 | 14 | 14 |
| Texas | 13 | 13 | 0 | 13 | 13 |
| Utah | 9 | 8 | 1 | 7 | 7 |
| Vermont | 44 | 45 | -1 | 45 | 45 |
| Virginia | 25 | 25 | 0 | 25 | 27 |
| Washington | 19 | 19 | 0 | 16 | 16 |
| West Virginia | 23 | 22 | 1 | 22 | 22 |
| Wisconsin | 26 | 34 | -8 | 35 | 36 |
| Wyoming | 1 | 1 | 0 | 1 | 1 |
| District of Columbia | 47 | 47 | 0 | 48 | 48 |
Was this page helpful to you?
Thank You!
The Tax Foundation works hard to provide insightful tax policy analysis. Our work depends on support from members of the public like you. Would you consider contributing to our work?
Contribute to the Tax Foundation
Share This Article!
Let us know how we can better serve you!
We work hard to make our analysis as useful as possible. Would you consider telling us more about how we can do better?